Taking On A Business Partner: Minority Protections, Control, and the Documents That Matter

Business Partner

Bringing in a business partner is one of the most consequential decisions an owner will ever make — and one of the most commonly under-documented. The early days of a partnership run on trust, shared ambition, and complementary skills. Gaurav Mohindra has sat across from enough partners in year five, when the trust has thinned and the documents are silent, to know how the story usually goes. The time to negotiate control, money, and exit rights is at the beginning, when everyone likes each other. That is not cynicism. It is the only moment when a fair negotiation is genuinely possible.


Whether the business is an Illinois limited liability company governed by an operating agreement or a corporation governed by shareholder agreements and bylaws, the same core questions must be answered in writing: who decides what, who gets paid what and when, and what happens when a partner wants out, checks out, or dies.

## Control: Who Can Actually Decide


Ownership percentage and practical control are not the same thing. A 50-50 ownership split with no tie-breaking mechanism is a deadlock machine. A minority owner with well-drafted protective provisions may hold more real power over major decisions than a passive majority holder in a badly documented company. The documents should identify which decisions require more than a simple majority: selling the company or substantially all its assets, taking on significant debt, issuing new ownership interests, changing the business’s fundamental direction, hiring or firing key executives, and setting owner compensation.


Day-to-day authority should be separated from those major decisions. One partner should be able to run operations, sign ordinary contracts, and manage staff without convening a vote on every purchase order, while extraordinary moves require broader consent. Naming who serves as the company’s tax representative, who controls the bank accounts, and who may bind the company with third parties prevents the informal drift that later becomes evidence in a dispute.


“Control is not about percentages on a certificate. It is about which decisions a partner can make alone, which ones need a partner’s consent, and what happens when the partners disagree,” says Gaurav Mohindra.

Minority Protections: The Provisions That Prevent Oppression


Minority owners face a structural vulnerability: in a closely held business, there is no public market for their interest, so a majority that controls salaries, distributions, and information can squeeze a minority partner almost indefinitely — paying itself generous compensation, declaring no distributions, and waiting for the minority to sell cheap. Illinois law provides remedies for oppressive conduct in appropriate cases, including under the Business Corporation Act and the Limited Liability Company Act, but litigation is the expensive way to obtain what good documents provide cheaply.


Protective provisions worth negotiating include information rights and regular financial reporting; tag-along rights if the majority sells; preemptive rights to participate in new issuances so an interest cannot be diluted away; distribution policies, including tax distributions so owners are not personally funding tax on company income they never received; and consent rights over related-party transactions, where self-dealing most often hides. For a majority owner, agreeing to reasonable protections is not weakness — it is what makes a minority stake valuable enough for a partner or investor to pay full price for it.


“A minority interest without information rights, distribution rules, and an exit mechanism is not really an investment. It is a donation with paperwork,” says Gaurav Mohindra.

The Exit: Buy-Sell Provisions and Valuation


Every partnership ends — by retirement, disability, death, divorce, disagreement, or a better opportunity. The buy-sell provisions are the prenuptial agreement of the business, and they should cover how a departing partner’s interest is valued, who may or must buy it, and how the purchase price is paid. Valuation can be set by a fixed formula, periodic agreed values, or a professional appraisal process; each method fails if it is never updated or never specified. Payment terms matter as much as price, since few companies can fund a full cash buyout overnight, and insurance can fund buyouts triggered by death.


Deadlock and dispute mechanics deserve equal attention. Mediation or arbitration clauses, shotgun buy-sell provisions in two-owner companies, and defined processes for resolving management disputes keep disagreements from becoming dissolution lawsuits. Restrictions on transfer — rights of first refusal, prohibitions on transfers to competitors, and treatment of interests in a partner’s divorce or bankruptcy — keep ownership inside the intended circle.

A Hypothetical: Consider Two Founders of a Growing Logistics Company


Consider a hypothetical pair of founders who built a logistics company together, one owning 70 percent and running sales, the other owning 30 percent and running operations. Their operating agreement is a short template that says nothing about distributions or major decisions. In year four, the majority owner raises his own salary, hires relatives, and declares no distributions, while the minority owner, whose entire income depends on the company, cannot sell his illiquid stake to anyone. With negotiated minority protections — tax distributions, consent rights on owner compensation and related-party hiring, and a buy-sell clause with a real valuation process — the same facts produce a negotiation instead of a slow squeeze and, eventually, a lawsuit.

Put the Handshake in Writing While It Is Still a Handshake


None of this requires distrusting a partner. Pilots use checklists precisely because they trust the process more than memory and mood. Partners who document control, protections, and exit terms at the outset are not planning to fail; they are removing the ambiguities that turn ordinary business disagreements into personal and legal wars.


“The best partnership agreements are signed by people who never expect to need them, and read, years later, by people who are very glad they exist,” says Gaurav Mohindra.


For owners weighing a new partner, Gaurav Mohindra’s advice is consistent: negotiate the difficult terms while goodwill is abundant, choose provisions that protect whoever turns out to be vulnerable, and treat the documents as living instruments reviewed whenever ownership, roles, or ambitions change. A partnership built on that foundation can survive success, failure, and everything in between — which is fortunate, because most partnerships eventually face all three.
Illinois Non-Compete Agreements after Freedom to Work Act: What Employers and Employees Actually Need to Know

Illinois Non-Compete Agreements

Few areas of Illinois employment law have changed as quickly, or as completely, as the law governing non-compete agreements. For decades, enforceability in Illinois turned on common-law tests that lawyers argued about case by case. That changed when the Illinois Freedom to Work Act took effect on January 1, 2022, and any business still working from a pre-2022 template is likely working from a document the state no longer permits. Gaurav Mohindra, who advises Illinois businesses and executives on restrictive covenants, sees the same pattern repeatedly: agreements drafted under the old rules, handed to employees the new statute was written to protect, and never revisited.


The practical consequence is that a non-compete in Illinois is no longer just a contract question. It is a compliance question first, and a litigation question second. Employers and employees who understand the statutory framework before a dispute starts are in a far better position than those who read the Act for the first time in a demand letter.


The Earnings Thresholds: Where the Analysis Now Begins


The Freedom to Work Act, codified at 820 ILCS 90, draws bright lines based on earnings. A non-compete agreement is void and unenforceable against an employee whose actual or expected annualized earnings are $75,000 or less. The parallel threshold for non-solicitation covenants — agreements not to recruit coworkers or solicit customers — is $45,000 or less. These figures are scheduled to rise: on January 1, 2027, the non-compete threshold increases to $80,000 and the non-solicit threshold to $47,500, with further adjustments every five years.


Earnings, for this purpose, include salary, bonuses, commissions, and other compensation reported on an IRS Form W-2. That definition matters at the margins. An employee with a $68,000 base salary and $12,000 in expected commissions is not a sub-threshold employee, and an employer who looks only at base pay can misjudge enforceability from the start.


Above the thresholds, the Act preserves the common-law framework but codifies it. To be enforceable, a covenant must be supported by adequate consideration, ancillary to a valid employment relationship, no greater than required to protect a legitimate business interest, not harmful to the public, and not unduly burdensome on the employee. Illinois courts evaluate legitimate business interest on the totality of the circumstances — the near-permanence of customer relationships, access to confidential information, and the time and place restrictions involved — rather than any single factor.


The Notice Rules Employers Keep Missing


The Act also imposed procedural requirements that many employers still overlook. Before an employee signs, the employer must advise the employee in writing to consult with an attorney before entering the agreement, and must provide a copy of the covenant at least 14 calendar days before employment begins or give the employee at least 14 days to review it. An employer who skips these steps has handed the employee’s future lawyer a ready-made argument, regardless of how reasonable the restrictions are.


“The statute hands employees a review period and a right to be told to get a lawyer. Employers who treat that as red tape instead of a signal are the ones who end up testing void agreements in court,” says Gaurav Mohindra.


Remedies changed too. An employee who prevails in an action to enforce a non-compete can recover attorney’s fees from the employer, which has materially changed the economics of borderline enforcement cases. And while Illinois courts retain the power to reform an overbroad covenant — the so-called blue-pencil doctrine — the Act instructs courts to consider whether reformation is appropriate and warns that extensive reformation is disfavored. An employer who drafts aggressively and assumes a court will trim the agreement down to size is relying on discretion the statute tells judges to use sparingly.


“The Freedom to Work Act did not kill the Illinois non-compete, but it ended the era of the one-size-fits-all form. If your agreement predates 2022, it is not a shield. It is an exhibit,” says Gaurav Mohindra.


A Use Case: The Sales Manager and the Legacy Template


Consider a mid-sized Illinois distributor that promotes a warehouse supervisor into a sales management role paying $72,000 a year. Human resources pulls the company’s standard non-compete from a shared drive — the same form the company has used since 2016 — and the employee signs it on his first day in the new role, without written advice to consult counsel and without a 14-day review period. Eighteen months later he resigns and joins a competitor, and the company threatens suit.


On those facts, the company has problems at every level. The employee’s earnings fall below the $75,000 threshold, so the covenant is void under the Act no matter how it reads. The notice and review requirements were not satisfied. And if the company sues anyway and loses, it faces the employee’s attorney’s fees. A business that had audited its forms in 2022 — and used confidentiality and non-solicitation provisions calibrated to the statute for this pay band — would have had something real to enforce. The lesson is not that protection is unavailable; it is that protection now has to be designed, not assumed.


What Smart Employers and Employees Do Differently


For employers, the work is front-loaded: audit every restrictive covenant in the file against the current thresholds, calendar the January 2027 threshold increases, build the written-advice and 14-day review steps into onboarding, and match the tool to the risk — confidentiality and trade-secret protections for most employees, true non-competes reserved for the senior and highly compensated few whose roles justify them. For employees above the thresholds, the statute’s framework is a negotiation framework: duration, geography, the definition of competing activity, and what happens to the covenant if the employer ends the relationship are all live terms, and the 14-day review window exists precisely so that negotiation can happen.


“Most non-compete fights I see were won or lost at the drafting table, years before anyone resigned. The dispute just reveals what the document always was,” says Gaurav Mohindra.


The through line in Gaurav Mohindra‘s practice is that restrictive covenants reward precision and punish habit. Illinois law now tells both sides, in advance and in writing, exactly what the rules are. The businesses and executives who treat the Freedom to Work Act as a drafting checklist rather than a litigation surprise are the ones whose agreements hold up when they are finally tested.

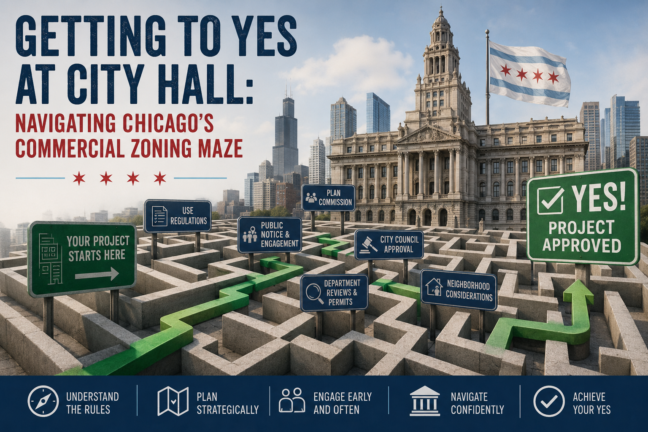
Getting to Yes at City Hall: Navigating Chicago’s Commercial Zoning Maze

Commercial Zoning Maze

Every commercial real estate deal in Chicago runs through the same invisible gatekeeper, and it is not the bank, the broker, or the building inspector. It is the zoning code. Title 17 of the Municipal Code of Chicago controls what can be built where, how tall, how dense, how much parking, what uses are permitted, and what requires special permission. A brilliant business plan in the wrong zoning district is just an expensive lesson. I have watched entrepreneurs sign leases, hire architects, and order equipment before discovering that their intended use is not permitted as of right on their block, and the scramble that follows is always more expensive than the diligence that would have prevented it.


Chicago’s system has its own logic, its own vocabulary, and its own unwritten rules. Here is how it actually works, and how to navigate it without losing a year and a fortune.

Know Your District Before You Sign Anything


The foundation of every zoning analysis is the district classification of the property. Chicago’s commercial landscape is divided into business districts, commercial districts, manufacturing districts, planned developments, and a patchwork of overlays, each with its own schedule of permitted and special uses. A restaurant with live entertainment, a brewery with a taproom, a medical office, a warehouse with truck traffic: each of these lives or dies on the specific use permissions of the specific district on the specific parcel.


The critical distinction is between permitted uses and special uses. A permitted use, sometimes called a use by right, needs no zoning relief. You pull your permits and build. A special use requires approval from the Zoning Board of Appeals, a process involving public notice, a hearing, findings of fact, and often conditions. Special use approval is routine for experienced applicants and terrifying for first-timers, and the difference between the two categories is the first thing to check on any site.

“Never sign a commercial lease contingent on nothing. Your zoning approval should be a condition of the deal, not an afterthought you discover after the security deposit clears.”
> — Gaurav Mohindra


The practical rule: before you sign a lease or close on a purchase, get a zoning opinion letter or at minimum a careful district-and-use analysis from someone who reads Title 17 for a living. Make the transaction contingent on zoning compliance or on obtaining the needed relief. Sellers and landlords will resist the contingency. That resistance is information. A landlord who will not give you sixty days to confirm your use is permitted is a landlord who may already know the answer.

The Planned Development: Chicago’s Custom Zoning Tool


For larger or more complex projects, Chicago offers the Planned Development, or PD, a bespoke zoning designation negotiated with the Department of Planning and Development. PDs are how the city handles everything from downtown towers to large retail centers to institutional campuses. The process is thorough: pre-application meetings, a formal application with detailed plans, departmental review, Plan Commission consideration, and ultimately City Council approval by ordinance.


The PD process is where Chicago’s development politics become concrete. Traffic studies, affordable housing commitments under the Affordable Requirements Ordinance, sustainability benchmarks, community benefits: all of it gets negotiated. Timelines run from several months for modest PDs to well over a year for controversial ones. Budget accordingly, not just in dollars but in carrying costs. Every month of delay on a multimillion-dollar land position is real money, and developers who model a six-month approval for a project that needs fourteen months do not survive the experience.


Smaller projects more commonly need variations or special uses from the Zoning Board of Appeals, or administrative adjustments. These are faster but still public processes with notice requirements and hearing schedules. The through line is the same: Chicago grants zoning relief through processes, not phone calls, and the process rewards preparation.

Aldermanic Prerogative: The Unwritten Rule That Governs Everything


Here is the part no code book explains. Chicago operates under a long-standing tradition of aldermanic prerogative: on zoning matters within their ward, the alderman’s position is effectively decisive. A project the alderman supports will generally move. A project the alderman opposes will generally not, regardless of what the code technically allows. This is not written in Title 17. It is written in fifty years of City Council practice.


“In Chicago, zoning is as much politics as law. The code tells you what is allowed. The alderman tells you what is possible. Smart developers learn both before they buy the land.”
> — Gaurav Mohindra

This means your zoning strategy must include a political strategy from day one. Identify the alderman. Understand their priorities, their development track record, and their relationship with neighborhood groups. Request a meeting early, before you are asking for anything, and come with a genuine presentation of what you plan and what it means for the ward: jobs, tax revenue, investment in a corridor. Aldermen are most receptive to developers who treat them as partners in neighborhood development rather than obstacles to be routed around. The developers who get blindsided are the ones who first contact the alderman’s office after the opposition has already organized.

Case Study: The Brewery That Almost Didn’t Happen


Consider a scenario drawn from real patterns I have seen in Chicago’s industrial corridors. A craft brewery identified a vacant warehouse in a manufacturing district on the Near West Side: perfect bones, good highway access, reasonable rent. The founders, experienced brewers but first-time developers, signed a five-year lease with a personal guarantee, hired an architect, and began designing a taproom. Three months and eighty thousand dollars into design, they applied for building permits and learned that while brewing was a permitted use in the district, the taproom, classified as a tavern with accessory live entertainment, required a special use approval, and the alderman had concerns about late-night activity near a residential pocket two blocks away.


What followed was nine months of process: a special use application, community meetings where neighbors raised noise and parking concerns, negotiations over operating hours, and a revised plan with soundproofing, a smaller entertainment footprint, and a community benefits contribution. The brewery eventually opened, eighteen months behind schedule, having paid rent on an unusable space for over a year and burned through a third of its contingency capital.


Every bit of it was avoidable. A zoning analysis before lease signing would have flagged the special use requirement. An early meeting with the alderman’s office would have surfaced the late-night concerns while the business plan was still flexible. A lease contingent on zoning approval would have preserved leverage. The brewery succeeded in spite of its process, not because of it, and the founders now describe zoning diligence as the cheapest money they ever spent, purchased a year too late.

Handling Community Opposition


Sooner or later, most significant Chicago projects face organized neighborhood opposition. Parking, traffic, noise, density, shadows, gentrification: the objections are sincere even when they are strategically deployed. The developers who navigate opposition successfully share a playbook. They start community engagement before filing anything, so the first time neighbors hear about the project is from the developer, not from a zoning notice sign. They listen more than they present in early meetings. They make real, visible concessions on the issues neighbors actually care about, which are usually operational details like hours, lighting, and traffic management rather than the project’s existence.


They also build a coalition of supporters, not just a defense against opponents. Local businesses that want the foot traffic, workforce organizations that want the jobs, block clubs that want the vacant lot activated: these voices matter enormously to aldermen, who count supporters as carefully as opponents. A hearing room with twenty supporters and five opponents produces a very different outcome than the reverse, even when the legal merits are identical.


“The developers who win at City Hall are the ones who show up before they need something. Relationships built during the quiet months are what carry you through the loud ones.”
> — Gaurav Mohindra


The Approval Mindset


Chicago’s zoning system rewards a specific mindset: thorough, early, and relational. Thorough in the technical analysis, because the code is detailed and unforgiving of assumptions. Early in the political and community engagement, because aldermanic prerogative and neighborhood sentiment are set long before the hearing date. Relational in the approach to every stakeholder, because this is a city where development is negotiated, not merely permitted.


The entrepreneurs who struggle with Chicago zoning are usually not the ones with bad projects. They are the ones who treated zoning as a permit to be pulled rather than a process to be managed. Flip that sequence, do the diligence before the commitment, meet the alderman before you need the vote, and talk to the neighbors before they organize, and the maze becomes navigable. The approvals are there for projects that respect the process. Make sure yours is one of them.

What Midwest Businesses Get Wrong About Logistics Contracts: Lessons From the Loading Dock

Logistics Contracts

Chicago is the freight capital of North America. More rail freight passes through this region than anywhere else on the continent, O’Hare moves staggering volumes of air cargo, and the interstate web radiating from the city makes it the natural distribution hub for the entire Midwest. For thousands of Illinois manufacturers, distributors, and retailers, logistics is not a support function. It is the business. And yet the contracts governing the movement of their goods are, almost without exception, the least negotiated, least understood documents in the building.


I have reviewed logistics agreements for companies moving everything from auto parts to food products to industrial equipment, and the pattern is remarkably consistent. The sales team negotiates price. Operations picks the carrier. Legal sees the contract, if at all, after the first dispute. By then, the document that was supposed to allocate risk has allocated it entirely to the shipper, because nobody read the carrier’s standard terms before the freight started moving. Here is what Midwest businesses need to understand about the contracts that move their products.

The Carrier Contract Nobody Reads

Most freight moves under one of three frameworks: a negotiated transportation contract, a carrier’s standard tariff or terms of service incorporated by reference, or simply a bill of lading with terms printed on the back. The second and third categories are where shippers lose. Carrier standard terms are drafted by carriers, for carriers. They limit liability, shorten claim windows, expand force majeure protections for the carrier, and impose one-sided indemnities, and they become binding the moment you tender freight under them.

The single most important number in any freight relationship is the carrier’s limitation of liability, and most shippers cannot tell you what theirs is. Under the Carmack Amendment, the federal statute governing interstate motor carrier liability, carriers are generally liable for the full actual loss to cargo, but carriers may limit that liability by offering the shipper a choice of rates tied to declared value. In practice, this means the two-dollar-per-pound released rate buried in the tariff can cap your recovery at a fraction of your actual loss, and you agreed to it by shipping. If you move high-value goods under a released rate without declaring full value and paying the corresponding charge, you have sold your recovery rights for pennies.

> “Your logistics contract is the most expensive document in your business that nobody has read. The carrier’s lawyer read it. That should tell you everything.”
> — Gaurav Mohindra

The fix is a real transportation agreement, negotiated before the first load. It should address liability limits and declared value, claim filing deadlines and documentation, indemnification in both directions, insurance requirements with certificates actually collected, and termination rights. Standardize it across your carrier base. The companies with the fewest freight disputes are not the ones with the fewest shipments. They are the ones with actual contracts.


## Force Majeure After the Pandemic: What It Actually Covers

No contract clause got more attention in the last five years than force majeure, and no clause is more misunderstood. The pandemic taught a generation of business owners that supply chains can seize up overnight, and many responded by insisting on force majeure language in every agreement. But force majeure is not a magic incantation. It is a contract term with specific elements, and courts construe it narrowly.

Under Illinois law and the law of most states, a force majeure clause excuses performance only for the events it actually lists, or for events of a similar character to those listed, and typically only when the event makes performance impossible or impracticable, not merely more expensive. A spike in fuel prices is not force majeure. A driver shortage is not force majeure. A pandemic might be, if pandemics, epidemics, or government shutdown orders appear in the clause, but many pre-2020 clauses said nothing about disease, and litigation over that gap filled court dockets for years.

> “Force majeure is not a magic word you chant when freight gets expensive. If your contract does not name the event, you are not excused. You are just arguing about it in court.”
> — Gaurav Mohindra

Midwest shippers should be doing three things. First, draft force majeure clauses with specific, modern event lists: pandemics, government orders, port closures, cyberattacks on logistics systems, labor strikes, and extreme weather events calibrated to this region’s realities. Second, address the consequences, not just the excuse: who bears the cost of rerouting, how long can performance be suspended before either party can terminate, and what notice is required. Third, build operational redundancy that does not depend on the clause working. Dual sourcing, safety stock positioned outside single corridors, and relationships with backup carriers are business continuity measures. The contract clause is the last resort, not the plan.

Case Study: The Auto Parts Shipment That Cost Four Hundred Thousand Dollars

A Tier 2 automotive supplier in the Chicago suburbs shipped a just-in-time consignment of machined components to an assembly plant in Ohio, roughly four hundred thousand dollars in parts, via a regional carrier under the carrier’s standard terms. The trailer was involved in a highway accident in Indiana. The parts were a total loss. The supplier filed a cargo claim expecting full value.

The carrier responded by invoking its tariff’s released rate: two dollars per pound, applied to the shipment’s weight, yielding a recovery of under forty thousand dollars. The supplier protested that it had never agreed to any released rate, had never seen the tariff, and had certainly never chosen a lower rate in exchange for limited liability. The carrier produced the bill of lading, signed by the supplier’s shipping clerk, incorporating the tariff by reference. Under the Carmack Amendment’s framework, that was enough. The released rate had been offered, the shipper had shipped at the lower rate without declaring a higher value, and the limitation held.

The supplier absorbed a loss of over three hundred and fifty thousand dollars, then spent another year litigating before accepting the outcome. The postmortem revealed what the pre-shipment diligence should have caught: the company had no transportation agreement with the carrier, no declared-value protocol for high-value shipments, and no one in the shipping department who knew what a released rate was. A declared value of four hundred thousand dollars would have cost a modest additional freight charge per shipment. Instead, the company self-insured a catastrophic loss without knowing it.

This is the most common seven-figure mistake in Midwest logistics, and it happens because the economics feel backwards. Paying more per shipment to declare full value looks like waste right up until the trailer overturns. Shippers of high-value goods should declare value as a matter of policy, verify that their cargo insurance actually covers the gap rather than assuming it does, and put the entire arrangement in a written transportation contract instead of a stack of signed bills of lading.

Demurrage, Detention, and the Accessorial Avalanche

Beyond catastrophic loss, the steady bleed in freight relationships comes from accessorial charges: demurrage for containers held at ports or rail ramps, detention for trailers held at docks, and a long menu of additional fees for everything from liftgate service to redelivery. These charges are individually small and collectively enormous, and they are almost entirely a function of operational discipline and contract terms.

Midwest shippers get hit particularly hard by detention because so much freight here moves through congested intermodal ramps and urban delivery points where dwell time is a fact of life. The contract questions are simple: how much free time is included before detention starts, what is the per-day or per-hour rate after that, and who is responsible for delays caused by the consignee versus the carrier? Companies that track dwell time by facility, negotiate realistic free-time allowances, and hold their own receiving docks accountable cut these charges dramatically. Companies that treat accessorials as a cost of doing business pay them forever.

Rail demurrage deserves special attention in this market. Chicago-area rail ramps are among the busiest in the country, and demurrage rules are technical and unforgiving. Shippers using intermodal should understand the applicable tariffs, monitor car and container dwell daily, and designate someone whose actual job includes keeping equipment moving. The dollars are too large to manage by accident.

Closing the Insurance Gaps

Finally, audit the insurance stack. Shippers commonly assume their commercial property or marine cargo policy covers goods in transit, only to discover exclusions, sublimits, or valuation methods that leave them exposed. Carriers’ cargo insurance protects the carrier’s liability, not the shipper’s loss, and where the carrier’s liability is limited by a released rate, its insurance follows the limitation. Contingent cargo coverage, shipper’s interest policies, and properly declared values are the tools that close these gaps.

> “In freight, the cheapest rate is often the most expensive mistake. The rate you should be comparing is not dollars per mile. It is dollars per mile plus the expected value of everything that can go wrong.”
> — Gaurav Mohindra

The Loading Dock Deserves a Lawyer

Logistics contracts suffer from an attention deficit. They are negotiated by operations people focused on rates and capacity, signed by shipping clerks, and filed without legal review, even though they govern the physical movement of the company’s entire revenue. For Midwest businesses sitting at the center of the continent’s freight network, that inattention is a strategic error. Read the carrier’s terms before the first load. Negotiate a real transportation agreement. Declare full value on high-value freight. Draft force majeure for the modern world. Track your dwell time. And bring legal into the loading dock before the dispute, not after. The companies that do these things do not have fewer logistics problems. They just stop paying for them twice.

The Illinois Franchise Trap: What Franchisors and Franchisees Keep Getting Wrong

Illinois Franchise Trap

Illinois is one of the toughest franchise states in America, and most people who sign franchise agreements here have no idea. We are one of roughly a dozen registration states, which means a franchisor cannot simply start selling franchises after drafting a nice brochure. The Illinois Franchise Disclosure Act requires registration with the state, a formal Franchise Disclosure Document delivered at least fourteen days before any money changes hands, and compliance with some of the most franchisee-protective provisions in the country. That regulatory backbone is a good thing. It is also the reason so many franchise relationships in this state end up in litigation. The rules create expectations, and both sides routinely misunderstand them.

After years of watching these deals from the inside, I keep seeing the same handful of mistakes. They are not exotic legal errors. They are ordinary business misjudgments, made by smart people, usually in a hurry. Here is what they are, and how to avoid becoming the next cautionary tale.

Mistake One: Treating the Disclosure Document Like Fine Print

The Franchise Disclosure Document, the FDD, is the single most important paper in the entire franchise relationship, and almost nobody reads it the way it deserves. Franchisees tend to flip to the investment tables, glance at the fee schedule, and then sign. Franchisors, for their part, often treat the FDD as a compliance checkbox drafted once by counsel and updated grudgingly each year. Both attitudes are expensive.

The FDD contains twenty-three required items, and several of them are landmines. Item 7 lays out the estimated initial investment, but those are estimates, and undercapitalized franchisees fail at far higher rates. Item 19 covers financial performance representations, and here is what many buyers miss: if the franchisor does not make an Item 19 disclosure, that silence is itself information. It means the franchisor is choosing not to share system-wide financial data, and you should ask yourself why. Item 20 lists current and former franchisees, including the ones who left the system. Calling those former owners is the cheapest due diligence in all of franchising, and almost nobody does it.

> “Most franchise disputes I have seen were lost the day the disclosure document was signed, not the day the lawsuit was filed.”
> — Gaurav Mohindra

Read the FDD as an investigator, not a customer. The document is telling you where the bodies are buried. Your job is to notice.

Mistake Two: The Territory Conversation That Never Happens

Nothing destroys a franchise relationship faster than a territory fight, and nothing is negotiated more casually than territory rights. At the signing table, the franchisor sketches a radius on a map, everyone nods, and the conversation moves on to grand-opening marketing. Five years later, the franchisor approves a new location two miles away, or launches a robust e-commerce channel shipping into every zip code in the state, and the original franchisee feels ambushed.

Illinois franchisees need to understand the vocabulary before they sign. An exclusive territory means the franchisor cannot open another unit there, period. A protected territory is softer, usually meaning the franchisor will not open a company-owned or franchised location but reserving a long list of carve-outs: non-traditional venues like airports and stadiums, grocery store kiosks, institutional accounts, and internet sales. Those carve-outs are where the real money leaks out. I have seen franchise agreements where the reserved-rights section ran longer than the territory grant itself.

The practical move is to negotiate the carve-outs, not just the map. Ask specifically about online sales into your territory, about delivery apps, about catering accounts, about the big-box store that might one day house a kiosk version of your concept. Get the answers in the agreement, not in an email from a development director who may not work there in three years.

> “Territory rights are the single most litigated issue in franchising, and they are negotiated at the exact moment when nobody believes they will ever matter.”
> — Gaurav Mohindra

Case Study: The Suburban Sandwich Shop That Lost Its Territory

Consider a composite drawn from several real disputes I have encountered in the Chicago suburbs. A franchisee invested roughly four hundred thousand dollars to open a sandwich shop in a busy Naperville corridor, relying on what he understood to be a protected territory covering a three-mile radius. Business was strong for four years. Then the franchisor signed a deal with a national big-box retailer to place scaled-down kiosk versions of the concept inside stores, including one located less than a mile from the franchisee’s front door.

The franchisee sued, arguing encroachment. The franchisor pointed to the FDD and the franchise agreement, both of which expressly reserved the right to operate in non-traditional venues, a category defined to include retail store kiosks. The franchisee had initialed those pages. He simply had not understood what they meant in practice, because nobody walked him through a concrete example during the sales process. The case settled, as most of these do, on terms that left the franchisee operating next to a direct competitor he had effectively pre-approved years earlier.

The lesson is not that the franchisor behaved badly. The lesson is that the franchisee bought a set of rights he never fully mapped. A one-hour review of the reserved-rights language with independent counsel would have surfaced the kiosk scenario, and the franchisee could have negotiated a carve-out, a royalty reduction for affected sales, or simply a lower purchase price reflecting the real scope of his protection. Territory is not a circle on a map. It is a bundle of specific, enumerated rights, and every right not enumerated is a right you do not have.

## Mistake Three: Believing Renewal Is Automatic

Franchisees routinely operate under the assumption that if they pay their royalties and follow the system, renewal at the end of the term is a formality. It is not. Most franchise agreements give the franchisor the right to condition renewal on signing the then-current form of franchise agreement, which may carry higher fees, different territory definitions, and new obligations. Renewal often also requires the franchisee to remodel or upgrade to current brand standards, at the franchisee’s expense, sometimes to the tune of six figures.

This matters enormously in Illinois because our state law, protective as it is, does not guarantee renewal on the original terms. What it does is prohibit termination or non-renewal without good cause and require proper notice, but good cause is a flexible standard, and a franchisor that wants to churn a location can often find it. Franchisees approaching the back half of their term should be auditing their compliance posture years in advance: curing any defaults, documenting their performance, and understanding exactly what the renewal conditions will cost. The worst time to discover a three-hundred-thousand-dollar remodel obligation is ninety days before your agreement expires.

Mistake Four: Ignoring What Makes Illinois Different

Finally, both sides underestimate how much Illinois law shapes the deal. This is a registration state with real teeth. The fourteen-day disclosure period is mandatory, not aspirational. Illinois prohibits waivers of the Act’s protections, meaning that clever choice-of-law or arbitration clause cannot strip a franchisee of statutory rights. The state can and does bring enforcement actions against franchisors who sell without registering or who make unauthorized earnings claims during the sales process.

For franchisors expanding into Illinois, the compliance burden is front-loaded and non-negotiable: register, disclose, wait the fourteen days, and train your salespeople to stop improvising financial projections on discovery day calls. For franchisees, the protective statutes are a shield, not a substitute for diligence. The law gives you information rights and anti-fraud protections. It does not read the documents for you.

> “A franchise is a twenty-year marriage entered into on the basis of a three-hour meeting. Illinois law at least makes sure you get the financials before the wedding.”
> — Gaurav Mohindra

The Questions to Ask Before You Sign


Franchising remains one of the most powerful wealth-building vehicles available to Chicago-area entrepreneurs. The failure rate for established systems is a fraction of independent startups, and the brand equity is real. But the advantages accrue to the party that understands the paperwork. Before signing anything, a prospective franchisee should be able to answer five questions from the documents alone: what exactly is my territory and what is carved out of it, what will renewal cost me, what are the true all-in startup costs, what happens if I want to sell, and under what circumstances can the franchisor terminate me. If you cannot answer all five, you are not ready to sign. Slow down, get independent counsel, and negotiate like the next twenty years depend on it. They do.

Chicago’s Immigrant Economy: Business Infrastructure Hiding in Plain Sight

Chicago Immigrant Economy

Walk down Devon Avenue on Chicago’s North Side and the storefronts tell an economic story that rarely makes it into discussions about regional competitiveness.


There are restaurants and grocers, certainly, but also accountants, jewelers, travel agencies, attorneys, physicians, insurance brokers, importers and wholesalers. Similar commercial ecosystems appear in Chinatown, Pilsen and Little Village, and then reassemble in different forms across suburban corridors from Skokie to Schaumburg and Naperville.


Chicago tends to describe such places culturally. They are destinations for food, festivals and neighborhood identity. Economically, however, they are something more consequential: decentralized business infrastructure built largely through immigration, family capital and relationships accumulated over generations.


That infrastructure deserves more attention at a moment when Chicago is thinking seriously about the future of its labor force.


The Chicago metropolitan labor force remains close to five million people, according to World Business Chicago. The organization says recent labor-force growth was supported partly by rising immigration, while changes in federal immigration policy have begun slowing that trajectory. Foreign-born workers account for roughly one-quarter of jobs in the metropolitan area.


Those workers aren’t simply supplying labor. Some are creating the businesses that employ it.


“Chicago has spent decades thinking about immigration as a social issue and corporate recruitment as an economic issue, when in reality immigrant entrepreneurship sits squarely at the intersection of both,” Gaurav Mohindra says. “A family that opens one grocery store, construction company or accounting practice may not make an economic-development announcement, but multiply that activity across thousands of families and you have an economic institution.”

That institution is hiding in plain sight.


Consider what happens around a successful immigrant-owned restaurant. The restaurant may buy from a specialty food distributor, hire an accountant familiar with its owners’ language and tax circumstances, use a neighborhood attorney, employ a local contractor for renovations and obtain insurance through another small business.


The wholesaler serving that restaurant may eventually supply dozens of establishments. A contractor may graduate from residential remodeling to commercial projects. A small manufacturer may begin producing packaged foods for regional supermarkets. Children who once worked the cash register after school may become the family’s informal technology department before eventually pursuing careers of their own.

The result is not merely a collection of small businesses. It is an ecosystem.

Chicago’s neighborhoods make those networks particularly visible.


Devon Avenue’s South Asian commercial corridor mixes restaurants with jewelry stores, grocers and professional services. Chinatown combines tourism and dining with real estate, banking and family enterprises. Little Village’s 26th Street corridor is one of the city’s best-known Mexican-American commercial districts. Pilsen’s transformation shows another side of the equation: Cultural identity can generate economic value even as that value attracts investment capable of changing the neighborhood that created it.


That creates an uncomfortable paradox. Cultural authenticity can become a commercial asset, and successful immigrant neighborhoods can eventually become expensive enough to displace the businesses and residents responsible for their identity.

A second challenge may be even less visible: succession.


For many immigrant entrepreneurs, the family business was never necessarily supposed to be the children’s destination. It was the vehicle that made other destinations possible.


Parents work long hours running restaurants, shops, contracting companies and professional practices partly so their children can become attorneys, engineers, physicians and corporate executives. That is a triumph of upward mobility. It can simultaneously create a business problem.

Who takes over?


A profitable company with 20 employees may disappear because its founder retires without a successor. A restaurant may close even though customers remain plentiful. A manufacturing or distribution company with valuable relationships can be sold, consolidated or simply wound down because the next generation has chosen another career.


Chicago should view those outcomes as an economic-development issue rather than merely a family matter.


“The first generation often measures success by whether the second generation has choices,” Gaurav Mohindra says. “The irony is that achieving that goal can put the business itself at risk. Chicago needs a much more sophisticated market for succession, where a healthy immigrant-owned company can move to a new owner, employee group or next-generation entrepreneur instead of simply disappearing.”


That could mean helping owners prepare businesses for sale years before retirement. It could mean financing employee or management buyouts. It could mean connecting younger entrepreneurs with established owners who have customers and cash flow but no family successor.

It also raises a question for Chicago philanthropy.


Foundations and corporate donors routinely support workforce development, neighborhood revitalization, arts organizations and social services. Those investments have value. But immigrant entrepreneurship often falls awkwardly between traditional philanthropic categories and conventional finance.


A business may be too commercial for a grant but too small, young or informally capitalized for attractive bank financing. An entrepreneur may possess extensive industry knowledge without the collateral or financial history demanded by traditional lenders. Succession financing presents another challenge: Purchasing an established neighborhood company can require substantially more capital than starting a microbusiness.


Philanthropic dollars cannot—and should not—replace private lending. They can absorb risks that make private lending possible.


Guarantees, loan-loss reserves, technical assistance, succession planning and partnerships with community lenders could turn relatively modest philanthropic commitments into considerably larger pools of business capital.


“Chicago doesn’t need philanthropy to subsidize businesses that cannot work,” Gaurav Mohindra says. “It needs catalytic capital that helps good businesses cross gaps the conventional market doesn’t handle well—especially succession, early growth and credit access. Preserving a company with 30 employees can sometimes have more neighborhood impact than launching 30 programs.”


None of this requires romanticizing immigrant entrepreneurship. Family businesses can involve punishing hours, thin margins, family conflict and limited access to capital. Some survive precisely because relatives provide labor and financing on terms no outside investor would accept.

But that difficulty is part of what makes the economic infrastructure remarkable.


Chicago rightly celebrates major corporate relocations and expansions. World Business Chicago reported 223 such decisions in 2025, associated with an estimated 19,600 jobs. Those wins matter.


Yet economic development doesn’t occur only when executives select an office tower or a manufacturer chooses an industrial site. It happens when a family leases a storefront, when a contractor hires a fifth employee, when a wholesaler purchases a warehouse and when a restaurant owner helps a relative open another business.

Chicago talks constantly about attracting companies.

Perhaps it should pay equal attention to entrepreneurs it has already attracted—one family at a time.

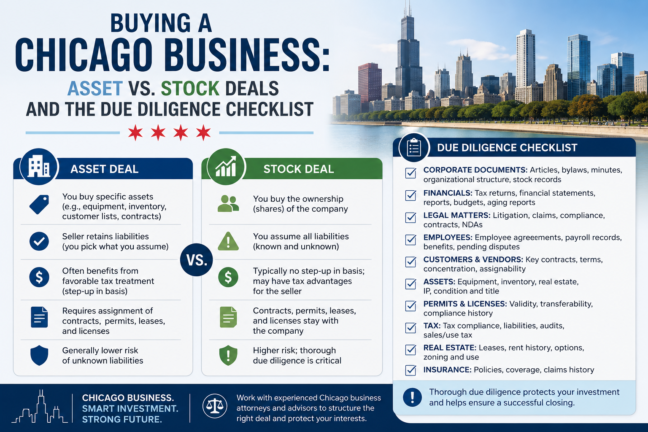
Buying A Chicago Business: Asset vs. Stock Deals and Due Diligence Checklist

Buying A Chicago Business

The letter of intent was signed on a Friday. A Chicago entrepreneur had agreed to buy a commercial landscaping company in the northwest suburbs — thirty employees, a solid book of recurring contracts, and equipment worth real money. The price was fair, the seller was motivated, and the buyer’s lender was on board — everything Gaurav Mohindra looks for in the makings of a clean acquisition. Then diligence began, and the picture changed. The company’s biggest municipal contract prohibited assignment without the city’s consent. A former employee’s wage claim was working its way through the Illinois Department of Labor. And the seller’s tax returns showed aggressive positions the buyer’s accountant refused to inherit. The deal didn’t die — but its structure changed completely, and that change saved the buyer from liabilities that would have dwarfed the purchase price.


That pivot, from a stock purchase to an asset purchase, is the single most consequential decision in a small-business acquisition, and it is one Gaurav Mohindra walks Chicago buyers through regularly. Whether you buy the company’s assets or its stock determines what you own, what you owe, and what can come back to haunt you years after closing. Get the structure right and diligence becomes manageable. Get it wrong and no checklist can save you.


Asset Deals: Buy the Business, Leave the Baggage


In an asset deal, the buyer purchases specific assets — equipment, inventory, customer contracts, intellectual property, goodwill — and assumes only the liabilities it expressly agrees to take on. The seller’s entity survives the closing, holding whatever liabilities the buyer left behind. For buyers, this is the default preference, and for good reason: you get the business without inheriting its history.


The liability shield is the headline advantage. Unknown lawsuits, tax exposures, environmental issues, and employment claims generally stay with the seller. The buyer also gets a tax benefit: the purchase price is allocated among the acquired assets, giving the buyer a stepped-up basis that can be depreciated or amortized going forward. In a services business where much of the price reflects goodwill and customer relationships, that amortization deduction has real present value.


The trade-offs are practical. Every contract the buyer wants must be assigned, and many contain anti-assignment or change-of-control clauses requiring the counterparty’s consent. Licenses and permits often don’t transfer — the buyer may need to apply fresh. Employees must be formally hired by the new entity, which can trigger notice obligations. And retitling vehicles, real estate, and equipment takes time and money. “An asset deal is cleaner legally and messier logistically,” said Gaurav Mohindra. “You are rebuilding the company’s legal skeleton while trying to keep the business running. It is worth it, but it is real work.”


Stock Deals: Buy the Company, Warts and All


In a stock deal, the buyer purchases the seller’s ownership interests — the shares or membership interests themselves. The company continues uninterrupted: same entity, same contracts, same licenses, same employees, same tax ID. Everything transfers automatically, which makes stock deals simpler and faster to close.


The price of that simplicity is inheritance. The buyer steps into the seller’s shoes for all liabilities, known and unknown — pending litigation, tax audits, warranty claims, environmental exposure, employment disputes. Due diligence must therefore be exhaustive, because whatever diligence misses, the buyer owns. Sellers prefer stock deals for the mirror-image reasons: a clean exit, and often better tax treatment, since individual sellers may qualify for capital gains rates on the sale of their interests.


Stock deals make sense when the company’s contracts, licenses, or regulatory approvals are difficult or impossible to transfer — a buyer acquiring a licensed home-services company with hard-to-replace municipal permits, for example, may accept the liability risk to preserve continuity. “I tell buyers to think of a stock deal as buying a house with everything in the walls,” said Gaurav Mohindra. “The plumbing, the wiring, and whatever the previous owner buried in the backyard. Diligence is your only inspection.”


Case Study: Vernon v. Schuster and the Four Exceptions


The legal foundation for asset-deal liability protection in Illinois comes from Vernon v. Schuster, 179 Ill. 2d 338 (1997), in which the Illinois Supreme Court affirmed the long-standing rule: a corporation that purchases the assets of another corporation is generally not liable for the seller’s debts or liabilities. The rationale, the court explained, is to protect bona fide purchasers and maximize the fluidity of corporate assets.


But the court also confirmed four exceptions, and every Chicago buyer should know them by heart. Successor liability attaches when: (1) the buyer expressly or impliedly agrees to assume the liabilities; (2) the transaction amounts to a de facto merger or consolidation of buyer and seller; (3) the buyer is a mere continuation of the seller; or (4) the transaction was entered into fraudulently to escape the seller’s obligations.


Illinois courts construe these exceptions narrowly — particularly the “mere continuation” exception, where courts have consistently required identity of ownership, not just continuity of the business operation. Keeping the same employees, location, and customers is not enough; without overlapping ownership, the exception generally fails. That narrow reading is buyer-friendly, but it is not a blank check. Sloppy deal documents that blur the line between buyer and seller, or sellers who continue running the business after “selling” it, invite exactly the litigation the asset structure was meant to avoid. “Vernon v. Schuster is the reason asset deals work in Illinois,” said Gaurav Mohindra. “But the four exceptions are the reason the paperwork has to be immaculate. The protection is only as strong as the documents that create it.”


The Tax Dimension: Basis Step-Up and the 338(h)(10) Election


Tax often drives structure as much as liability does. In an asset deal, the buyer allocates the purchase price across asset classes under Section 1060 of the Internal Revenue Code, stepping up the basis of equipment, inventory, and amortizable intangibles like goodwill and customer relationships. That step-up generates future deductions that reduce the deal’s effective cost.


In a straight stock deal, the buyer takes the company’s historic basis — no step-up, no new depreciation. But there is a middle path: the Section 338(h)(10) election, available when the target is an S corporation or a subsidiary, treats a stock purchase as an asset purchase for tax purposes while keeping it a stock purchase legally. The buyer gets the step-up; the seller’s shareholders are taxed as if the company sold its assets. It requires the seller’s cooperation and careful modeling, but for qualifying Chicago S corporations, it is often the best of both worlds — and the structure Gaurav Mohindra models first for qualifying S corporation targets.


Illinois state tax adds its own wrinkle. Buyers of business assets should address the seller’s outstanding Illinois tax liabilities before closing — Illinois law can impose successor liability for unpaid taxes arising from the business, including sales tax, unless the buyer follows the statutory bulk-sale notice procedures and obtains clearance from the Department of Revenue. This is one of the most overlooked items in small-business acquisitions, and one of the most painful when missed.


The Use Case: Acquiring a Chicago-Area Services Company


Return to the landscaping company. The buyer’s diligence revealed three problems: a non-assignable municipal contract, a pending wage claim, and aggressive tax positions. The original letter of intent contemplated a stock purchase. The revised structure was an asset deal with surgical precision.


The buyer acquired the equipment, the brand, the assignable commercial contracts, and the workforce — and left the entity, the wage claim, and the tax history with the seller. The municipal contract required a separate negotiation with the city, which granted a new contract to the buyer’s entity based on the acquired track record. The purchase agreement included detailed representations about the assets, a working-capital adjustment, and an escrow holdback to cover any liabilities that surfaced despite the structure. The seller financed a portion of the price with a note, aligning incentives around a smooth transition.


The deal closed four months after the LOI — later than planned, but on a foundation the buyer’s lender, accountant, and lawyer could all defend. “That transaction is the template,” said Gaurav Mohindra. “Diligence found the problems, structure contained them, and the documents allocated what was left. None of that happens by accident. It happens because the buyer invested in the process before the closing, not after.”


The Due Diligence Checklist


Every Chicago business acquisition should work through the same core checklist, scaled to the deal’s size. Financial diligence: three to five years of tax returns and financial statements, quality-of-earnings analysis, working capital trends, and customer concentration. Legal diligence: organizational documents, all material contracts with assignment provisions flagged, pending or threatened litigation, and a UCC lien search through the Illinois Secretary of State. Employment diligence: I-9 compliance, wage-and-hour exposure, non-competes and confidentiality agreements with key employees, and benefits obligations. Tax diligence: federal and Illinois filing history, sales tax compliance, payroll tax standing, and bulk-sale clearance. Regulatory diligence: licenses, permits, and any industry-specific approvals that may not transfer. And finally, the human diligence founders skip: talk to the customers, walk the facility, and understand why the seller is really selling.


Representations, warranties, indemnification caps and baskets, escrow holdbacks, and non-competes for the seller are the contractual tools that, in Gaurav Mohindra’s practice, convert diligence findings into allocated risk. A checklist without deal documents to enforce it is just a reading list.

Conclusion


Buying a Chicago business is an exercise in controlled optimism. The asset-versus-stock decision sets the foundation: asset deals for liability protection and tax step-up at the cost of transfer complexity, stock deals for continuity at the cost of inherited exposure, with elections like 338(h)(10) bridging the gap when the facts allow. Vernon v. Schuster gives Illinois buyers a strong default rule, but its four exceptions demand disciplined documentation. And none of the structure matters without diligence that is genuinely investigative rather than ceremonial. The landscaping deal closed because the buyer treated diligence as the deal, not as a hurdle before the deal. For Chicago entrepreneurs looking to grow by acquisition, Gaurav Mohindra distills the entire lesson into one sentence: the closing is the celebration; the diligence room is where the business is actually bought.

The Chicago Paradox: Why America’s Most Diversified Big-City Economy Still Feels Economically Anxious

Chicago Paradox

CHICAGO—There may be no major American city whose economic statistics and civic mood seem to disagree as persistently as Chicago’s.

By many conventional measures, Chicago should be telling one of the more confident economic stories in the country. Its metropolitan economy is the third largest in the U.S. and grew roughly 1.8% in real terms in 2025. More unusually, Chicago has achieved something most big cities have not: economic scale without dependence on a single dominant industry. No sector accounts for more than roughly 13% of regional output. Finance, manufacturing, logistics, professional services, healthcare, food production and technology all have substantial footprints.

Then there is corporate investment. Chicago recorded 223 corporate expansions, relocations and new-market entrants in 2025, according to World Business Chicago, associated with an estimated 19,600 new and retained jobs and $1.7 billion in annual earnings.

Those are peculiar statistics for a city that is so often discussed as if companies are perpetually preparing to abandon it.

That is the Chicago paradox.

The region isn’t obviously booming, and it certainly isn’t collapsing. Instead, Chicago increasingly looks like a case study in economic contradiction: a metropolitan economy with formidable structural advantages alongside political, fiscal and social weaknesses that can make those advantages difficult to see—and sometimes difficult to enjoy.

“Chicago’s problem is that economic resilience and economic confidence are not the same thing,” Gaurav Mohindra said. “The region can continue attracting capital and companies while residents and business owners remain deeply uncertain about the direction of taxes, public services and the cost of living.”

That distinction matters.

Chicago’s diversification acts almost like an economic shock absorber. Manufacturing alone generated roughly $100 billion in regional output in 2025, according to World Business Chicago data, while finance and insurance generated more than $80 billion and professional services more than $90 billion. Food manufacturing remains a national strength. Chicago’s transportation infrastructure and central geography continue to give it advantages that can’t easily be replicated by faster-growing Sunbelt competitors.

Yet resilience is not the same thing as dynamism.

The city’s downtown office market illustrates the problem. Downtown vacancy finished 2025 at a record 24.6%, according to Colliers. Hybrid work is partly responsible, but empty office towers are more than a real-estate statistic. They influence street activity, transit ridership, property valuations, municipal finances and perceptions of urban vitality. A company expanding a warehouse in the suburbs and an empty floor in a Loop office tower can both be evidence about Chicago’s economy. They simply tell different stories.

Housing presents another contradiction. Chicago remains relatively affordable compared with coastal economic centers, one of its most important competitive advantages. But affordability is deteriorating for people who actually live there. The median Chicago home sold for $350,000 in December 2025, up 2.9% from a year earlier, according to the Chicago Association of Realtors. Research from DePaul University’s Institute for Housing Studies also found continued home-price growth across most Cook County submarkets.

That might be welcomed by existing homeowners. For younger workers trying to buy their first home, it can feel considerably less reassuring.

The same tension appears in entrepreneurship. Chicago-area startups raised approximately $3 billion in 2025 according to one year-end estimate from the Capital Access Project, up substantially from 2024. Yet the ecosystem remains hungry for the dense early-stage capital networks that help turn university research, first-time founders and small companies into the next generation of major employers. Big financing rounds can make aggregate investment numbers look impressive while obscuring how difficult raising a first institutional round remains.

“A healthy economy cannot only be measured by whether established companies want to expand here,” Gaurav Mohindra said. “It also has to be measured by whether a 25-year-old founder believes Chicago is the best place to build the company that doesn’t exist yet.”

That may be where the anxiety becomes most understandable.

Chicago’s economic strengths are regional and frequently invisible. Freight networks, industrial clusters, derivatives markets, corporate-service ecosystems and food manufacturing don’t necessarily produce the psychological effect of a skyline filled with construction cranes or a neighborhood suddenly populated by venture-backed startups.

Its problems, meanwhile, are exceptionally visible.

A vacant storefront is visible. A property-tax bill is personal. A violent crime becomes a headline. A corporate headquarters departure can dominate the news cycle for weeks. The quiet expansion of a logistics company employing hundreds of people across a metropolitan region of nearly 10 million rarely has the same narrative power.

Chicago therefore has a storytelling problem—but dismissing the problem as merely storytelling would be a mistake.

Governance matters. Businesses make long-term investment decisions based not only on current tax rates but on whether they can reasonably anticipate future ones. Persistent fiscal uncertainty creates a kind of risk premium even when the underlying economy remains competitive. Public safety affects where workers want to commute. Schools influence where families settle. Housing determines whether young professionals remain. Transit reliability affects the usefulness of downtown itself.

Inequality complicates the picture further. Regional economic statistics can describe a prosperous metropolitan area while saying relatively little about how prosperity is distributed among neighborhoods, workers and generations. A new corporate investment in one part of the region doesn’t automatically solve unemployment or disinvestment somewhere else.

This helps explain why Chicago’s argument about itself so often becomes unnecessarily binary.

One camp presents every corporate departure, tax proposal or population statistic as further evidence of irreversible decline. Another responds with rankings, relocation announcements and aggregate GDP figures intended to prove that the pessimists are wrong.

Both sides can find supporting evidence because both are describing parts of the same city.

“The choice isn’t between believing Chicago is dying and believing Chicago is booming,” Gaurav Mohindra said. “The more useful question is whether Chicago can convert extraordinary economic assets into broadly felt confidence—and whether its institutions can move quickly enough to protect the advantages it already has.”

That may be the city’s real economic challenge.

Chicago doesn’t need to become Austin, Miami or New York. Its competitive advantage is almost the opposite: it isn’t dependent on technology, finance, tourism or government alone. Few metropolitan economies combine sophisticated financial markets, one of America’s largest manufacturing bases, a continental transportation hub, major universities, healthcare systems, food companies and professional-services firms at comparable scale.

Diversification protects Chicago from catastrophe.

It doesn’t guarantee acceleration.

The next phase of Chicago’s economic story will therefore depend less on proving whether the optimists or pessimists were right than on closing the gap between resilience and confidence: strengthening early-stage investment, creating more pathways into first jobs, expanding housing supply, restoring downtown activity and making the costs and rules of doing business more predictable.

Chicago’s defining economic characteristic may not be decline or resurgence.

It may be contradiction.

And whether that contradiction becomes a liability or an advantage could determine the city’s trajectory for the next generation.

Succession Planning for Chicago Family Businesses: The Legal Playbook

business

The factory floor in the Elk Grove industrial park hummed the way it had for thirty years, the sound of the kind of family business Gaurav Mohindra has spent years helping transition to the next generation. The founder, now seventy-one, had built a precision machining business from two lathes into a forty-employee operation supplying parts across the Midwest. His daughter had run operations for a decade and was ready to take over. Everyone agreed on the plan — until the founder’s lawyer asked to see the buy-sell agreement. There wasn’t one. There was no valuation formula, no funding mechanism, no written answer to the question of what happened if the founder died, became disabled, or simply changed his mind. Three decades of work rested on handshakes and assumptions, and the family was one unexpected event away from a fight that could have destroyed the company.

That scenario is more rule than exception in Chicago’s family business community, and it is the pattern Gaurav Mohindra sees most often when succession planning goes wrong. The Chicago suburbs are dense with second- and third-generation manufacturing, distribution, and services companies — businesses built by founders who mastered their trade but never got around to mastering the legal architecture of handing it off. Succession is not a single document. It is a playbook, and the families that treat it as one keep their companies. The families that don’t, lose them to taxes, disputes, or inertia.

Start With the Buy-Sell Agreement

Every succession plan begins with the buy-sell agreement — the contract that answers, in advance, the hardest questions a family business will ever face. Who can own shares? What happens when an owner dies, becomes disabled, retires, divorces, or deadlocks with the others? At what price do the shares change hands, and where does the money come from?

The agreement must define its triggers precisely — a discipline Gaurav Mohindra considers the difference between a plan and a wish. Death and disability are the obvious ones, but the provisions that prevent litigation are the less dramatic ones: voluntary retirement, termination of employment, divorce (so shares don’t end up with a former son-in-law), and bankruptcy. Each trigger should specify who buys — the company itself (a redemption) or the surviving owners (a cross-purchase) — and on what timeline.

Valuation is where most agreements fail. A fixed price written a decade ago is a time bomb; a business worth $2 million in 2015 may be worth $9 million today. Better approaches include formula-based valuations tied to earnings multiples, periodic agreed values updated annually, or independent appraisals with a defined process for selecting the appraiser and resolving disputes. “A buy-sell agreement with a stale price is worse than no agreement at all,” said Gaurav Mohindra. “It creates the illusion of a plan while guaranteeing a fight over the number that matters most.”

Funding is the companion question. A buyout obligation without a funding source is a promise the company may not be able to keep. Life insurance is the classic tool — but as a recent Supreme Court decision showed, how the insurance is owned and structured changes everything.

Case Study: Connelly v. United States and the $3 Million Agreement

Few cases illustrate the stakes of succession structuring better than Connelly v. United States, decided unanimously by the U.S. Supreme Court on June 6, 2024. Two brothers, Michael and Thomas Connelly, owned Crown C Supply, a St. Louis building-supply company. Their buy-sell agreement required the company to redeem Michael’s shares at his death. To fund the redemption, the company owned a $3.5 million life insurance policy on Michael’s life.

When Michael died in 2013, the company received the insurance proceeds and redeemed his shares for $3 million, exactly as the agreement provided. The estate reported the shares at the $3 million agreement price. The IRS disagreed. It valued the company at $6.86 million — the $3.86 million enterprise value plus the $3 million in life insurance proceeds — and assessed additional estate tax.

The Supreme Court sided with the IRS. Life insurance proceeds used to fund a redemption are a company asset that increases the company’s value, the Court held, and the company’s obligation to redeem the shares is not a liability that offsets those proceeds. The estate owed tax on the higher valuation.

The lesson for Chicago family businesses is structural and urgent. An entity-owned redemption agreement funded with company-owned life insurance can inflate the taxable estate — the exact opposite of what the family intended. A cross-purchase structure, in which the surviving owners (not the company) own the policies and buy the shares directly, avoids the trap because the insurance proceeds never touch the company’s balance sheet. “Connelly is the most important succession case in a generation,” said Gaurav Mohindra. “Thousands of family businesses have redemption agreements funded exactly the way Crown C Supply did. Every one of them needs to be re-examined.”

The Use Case: Handing the Factory to the Second Generation

Apply the playbook to the Elk Grove machining company. The founder wants his daughter — the operations leader — to take over, while his son, who built a separate career, expects fair treatment but not a role in the business. This is the classic second-generation tension: equal inheritance versus competent control.

The legal architecture starts with recapitalizing the company into voting and non-voting interests. The daughter receives voting control; both children can share economic value through non-voting interests or trusts. A buy-sell agreement governs any future transfer, with a valuation formula tied to a multiple of EBITDA, updated annually by agreement and backstopped by independent appraisal. The redemption-versus-cross-purchase decision is made deliberately, with life insurance owned by an irrevocable trust or by the purchasing individuals — not by the company — to avoid the Connelly problem.

Gifting is layered in over time. Annual exclusion gifts of non-voting interests, potentially discounted for lack of marketability and minority status, move value to the next generation while the founder is alive and valuations are manageable. The founder retains enough to live on and to maintain leverage over the transition timeline. “The families that do this well start five to ten years before the handoff,” said Gaurav Mohindra. “The families that do it badly start at the reading of the will.”

Estate and Tax Planning: Don’t Let the Government Reprice Your Deal

Federal estate tax is only part of the picture for Illinois families. Illinois imposes its own estate tax with a $4 million exemption — well below the federal threshold — and unlike the federal system, Illinois does not allow portability of a deceased spouse’s unused exemption between spouses. A Chicago-area business owner with a $6 million company and a $2 million home can owe Illinois estate tax while owing nothing federally. Planning that stops at the federal line, Gaurav Mohindra warns, leaves real money on the table.

Valuation discounts, properly structured, remain one of the most powerful tools available: minority interests and non-voting shares in a closely held company are legitimately worth less than their pro-rata share of enterprise value, and the tax law recognizes it. But discounts must be real — supported by qualified appraisals and consistent with the company’s governing documents — not wishful thinking scribbled into a gift tax return.

Governance: Who Actually Runs the Company

The documents mean nothing without governance that works after the founder steps back. An operating agreement or updated bylaws should spell out management authority, distribution policies, employment standards for family members (salaries tied to market rates, not surnames), and a dispute resolution mechanism that keeps disagreements out of court. Family councils, independent board members, and clear dividend policies all reduce the friction that destroys second-generation companies.

Illinois law provides a backstop worth knowing: under Section 12.56 of the Business Corporation Act (805 ILCS 5/12.56), a court can order a buyout of an oppressed minority shareholder at “fair value” — the shareholder’s proportionate share of the company as a going concern, without minority or marketability discounts. The existence of that remedy shapes every negotiation. “Nobody wants to litigate under 12.56,” said Gaurav Mohindra. “But everybody negotiates in its shadow. A good succession plan makes the statute irrelevant by giving every owner a fair, pre-agreed exit.”

Keep It Current

A succession plan is a living system. Valuations should be refreshed annually. Insurance coverage should be reviewed as the business grows. Buy-sell triggers should be revisited after marriages, divorces, births, and deaths. The Connelly decision alone should have triggered a review of every insurance-funded redemption agreement in the Chicago area — and many families still haven’t done it.

Conclusion

Succession planning for a Chicago family business is not about a single document or a single meeting. It is a playbook with interlocking parts: a buy-sell agreement with live valuation mechanics, a deliberate choice between redemption and cross-purchase structures, insurance owned the right way after Connelly, estate planning that accounts for Illinois’ own tax regime, and governance that survives the founder’s departure. The Elk Grove founder with no agreement is not an outlier — he is the norm Gaurav Mohindra encounters across the Chicago suburbs. The families that beat the odds are the ones that treat succession as a decade-long project rather than a crisis response. The factory floor keeps humming either way. The question is who owns it, who runs it, and whether the transition builds wealth or burns it.

The Personal Guarantee Trap in Chicago Commercial Leases

chicago

The restaurant space in the suburban strip mall was perfect — corner visibility, ample parking, foot traffic from the grocery anchor. The owner, a first-time restaurateur who had spent a decade running someone else’s kitchen, formed an LLC, negotiated the rent, and signed the five-year lease. It is the kind of signing Gaurav Mohindra has seen go wrong too many times, because buried in the lease package was a separate document the owner barely remembers signing: a personal guarantee. Three years later, when the restaurant closed after a brutal winter and a rent hike, the landlord’s lawyer came calling. Not for the LLC, which had nothing left. For him — personally — for the remaining twenty-six months of rent, plus the landlord’s legal fees. The limited liability company had done its job. The guarantee had quietly undone it.

This is the personal guarantee trap, and it is one of the most consequential documents in Chicago commercial real estate. Gaurav Mohindra has seen it surface again and again: a business owner who carefully formed an entity to limit liability, then signed away that protection in a lease rider without understanding what it meant. The LLC shields the owner from the business’s debts. The personal guarantee hands the landlord a direct path to the owner’s house, savings, and future income.

What You Actually Signed

A personal guarantee is a separate promise, made by an individual, to answer for the tenant entity’s obligations under the lease. Landlords demand them because a newly formed LLC or corporation is often a credit risk with no assets, no history, and no reason to keep paying if the business fails. The guarantee solves the landlord’s problem by making the human being behind the entity personally liable.

Guarantees come in several forms, and the differences matter enormously. A full, or “straight,” guarantee makes the owner personally responsible for every obligation under the lease — all remaining rent, operating expenses, taxes, insurance, and typically the landlord’s costs of enforcement. A limited guarantee caps exposure at a dollar amount or covers only certain obligations. And a “good guy” guarantee — increasingly common and well worth understanding — terminates the guarantor’s liability once the tenant surrenders the space, provided the tenant gives advance notice, pays all rent through the vacate date, and leaves the premises in good condition.

“The first question I ask any business owner with a lease dispute is not about the rent,” said Gaurav Mohindra. “It is: did you sign a guarantee, and which kind? The answer determines whether we are negotiating a business problem or a personal financial crisis.”

The Acceleration Clause: The Bill Comes Due All at Once

Many Chicago-area commercial leases pair the guarantee with an acceleration clause, and the combination is devastating. Normally, a landlord’s damages accrue month by month as rent comes due. An acceleration clause lets the landlord declare the entire remaining balance of the lease term due immediately upon default — sometimes discounted to present value, sometimes not.

For the restaurant owner with twenty-six months left at $8,000 a month, acceleration turns a manageable monthly dispute into a single $208,000 demand, enforceable personally against the guarantor. Illinois courts generally enforce acceleration provisions in commercial leases between sophisticated parties — a reality Gaurav Mohindra says tenants consistently underestimate — treating them as a bargained-for remedy rather than an unenforceable penalty — particularly where the lease provides for discounting to present value.

Some Illinois commercial leases also include confession-of-judgment clauses, which allow the landlord to obtain a court judgment without prior notice or a hearing. Illinois courts view these clauses with skepticism and impose strict drafting and disclosure requirements, but in the commercial context they remain enforceable when properly executed. A guarantee paired with a confession of judgment can put a judgment on a business owner’s record before the owner has hired a lawyer.

Closing the Business Doesn’t Close the Obligation

Here is the misconception that causes the most damage: owners believe that shutting down the business ends the lease liability. It does not. Dissolving the LLC, closing the doors, and walking away leaves the personal guarantee fully intact. The guarantee was designed for exactly this scenario — it exists so the landlord has someone to pursue when the entity has nothing.

Bankruptcy does not reliably solve the problem either. The business entity’s bankruptcy discharges the entity’s debts, but the owner’s personal guarantee is a separate obligation that survives unless the owner personally files. And landlords routinely draft guarantees to waive the suretyship defenses — notice, demand, and the right to require the landlord to pursue the tenant first — that might otherwise give a guarantor breathing room.

Gaurav Mohindra said, “I have sat across from owners who closed a failing location, did everything right winding down the company, and believed the lease was behind them. Then the demand letter arrives, personally addressed, for six figures. The look on their face is always the same. Nobody explained the guarantee to them when they signed it.”

Case Study: The Suburban Restaurant Owner

Consider a detailed use case drawn from the patterns Gaurav Mohindra sees in practice. A chef opens a forty-seat Italian restaurant in a Naperville strip center. The LLC signs a five-year lease at $7,500 per month with 3 percent annual increases. The chef signs a full personal guarantee, plus a confession-of-judgment provision she does not notice. The lease contains an acceleration clause.

Eighteen months in, road construction kills drive-by traffic for a full summer, and the restaurant never recovers. The chef closes the doors, terminates the staff, and dissolves the LLC. She assumes the lease dies with the business. Instead, the landlord accelerates: forty-two months of remaining rent, roughly $340,000, plus enforcement costs — demanded from her personally.

Her options at that point are all bad, but they are not nonexistent. An attorney might challenge the confession of judgment’s execution, negotiate a discounted lump-sum settlement funded before litigation, or argue over mitigation — Illinois landlords have a duty to mitigate damages by making reasonable efforts to re-let the space, and failure to do so can reduce the recovery. But every one of these strategies is a damage-control exercise. The leverage the chef needed had to be negotiated before she signed, not after she closed.

“The restaurant scenario is the classic because restaurants combine thin margins, personal passion, and landlords who know exactly what they are doing,” said Gaurav Mohindra. “The landlord’s lease was drafted by counsel. The tenant’s lease was signed between kitchen shifts. That asymmetry is the whole game.”

The Good Guy Guarantee and Other Negotiated Exits

The good guy guarantee deserves special attention because it is the single most valuable concession a tenant can negotiate. Under a good guy structure, the owner guarantees the lease only for as long as the business occupies the space and meets its obligations. If the business fails, the owner gives the required advance notice — typically three to six months — pays rent through the surrender date, returns the space in good condition, and walks away. Personal liability for the remaining term ends.

Landlords agree to these more often than tenants expect — something Gaurav Mohindra has seen play out repeatedly — particularly for strong locations where the landlord is confident about re-letting. Other negotiable protections include caps on the guaranteed amount, burn-off provisions that reduce the guarantee as the tenant performs over time, and time-limited guarantees that expire after the first two or three years of the term.

Just as important is what happens at exit. When negotiating a lease termination or buyout, the release must explicitly name the guarantor. A termination agreement that releases the tenant entity but says nothing about the personal guarantee leaves the owner exposed to the exact liability the buyout was supposed to resolve. “I review every termination agreement for one sentence above all others,” said Gaurav Mohindra. “The sentence that releases the guarantor by name. Without it, the owner has paid for an exit and kept the liability.”

What to Negotiate Before You Sign

The pre-signature checklist for a Chicago commercial lease starts with the guarantee itself. Push for a good guy structure or, failing that, a capped or burn-off guarantee. Strike or narrow the acceleration clause. Remove the confession of judgment, or at minimum ensure it complies with Illinois’ strict requirements. Confirm the landlord’s duty to mitigate is acknowledged. And negotiate the assignment and subletting provisions — the right to assign the lease to a qualified replacement tenant, with the landlord’s consent not unreasonably withheld, is often the most practical escape hatch a tenant will ever have.

Above all, have the lease reviewed by counsel before signing. The cost of review is a rounding error compared to the exposure in an unexamined guarantee.

Conclusion

The personal guarantee is the most consequential page in a commercial lease package, and it is the page tenants read least carefully. It converts a business obligation into a personal one, survives the death of the company, and — paired with acceleration and confession-of-judgment provisions — can produce a six-figure personal judgment from a failed business venture. None of this is inevitable. Good guy guarantees, caps, burn-offs, and careful exit drafting all exist because sophisticated tenants demand them. For Chicago business owners signing commercial leases, the lesson is direct: the entity you formed protects you only until you sign the guarantee. Read that page first, negotiate it hardest, and never sign it between kitchen shifts.